Commission revenue
Model eligible policies, average premium, retention, renewal price changes and expiring, renewal and new-business commission rates.
Insurance Agency Lab
Insurance Agency Lab is a specialized financial decision-support platform for independent agencies. It connects commission revenue, carrier contingencies and overrides, producer economics, staffing and operating costs to the profit and cash your agency can expect, and shows how each decision changes them.
$39.99per organization
per month
14-day free trial. No credit card required.
Already a customer? Sign in to Insurance Agency Lab
What you can evaluate
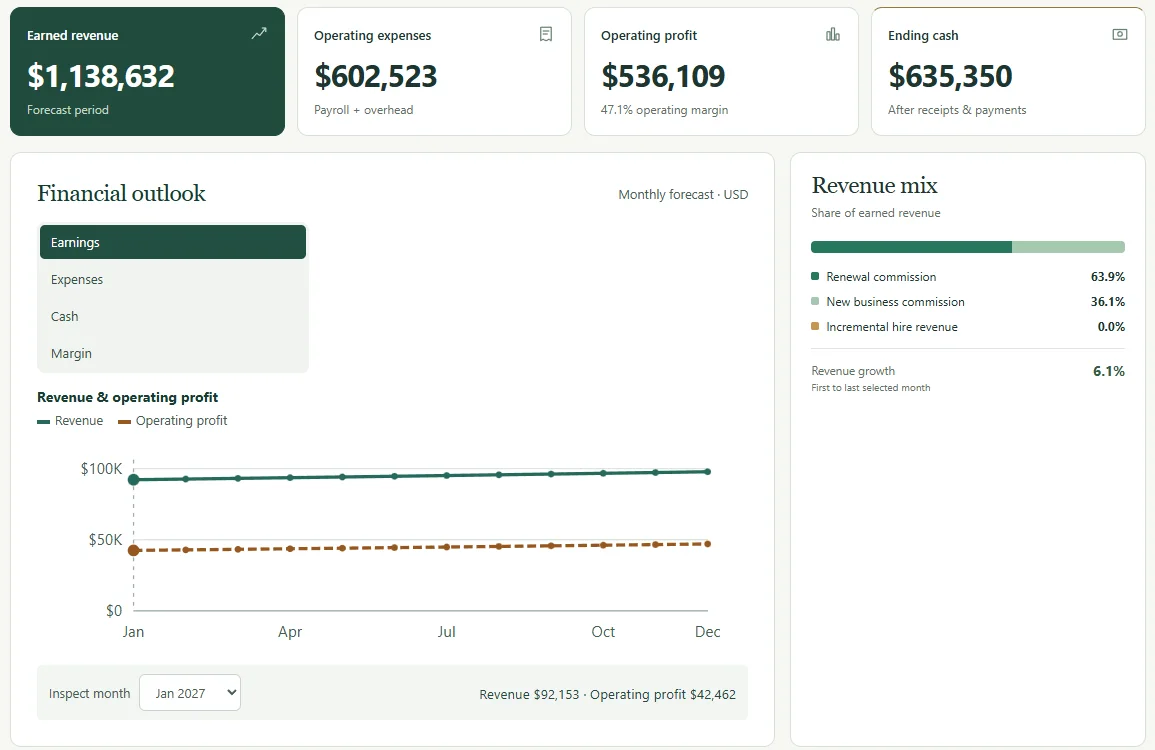
Insurance Agency Lab is a planning and decision-analysis tool. Each schedule feeds one twelve-month forecast, so a change in one place flows through to profit and cash.
Model eligible policies, average premium, retention, renewal price changes and expiring, renewal and new-business commission rates.
Set each producer’s new and renewal splits, salary and burden, and see the contribution each one adds after compensation.
Add a service or business-development role with a start month, pay, benefits and ramp, and test whether the hire pays for itself.
Plan technology, occupancy, marketing, professional services and other costs as fixed amounts or a share of revenue.
Follow earned revenue, operating profit and operating margin month by month, with a revenue mix by commission type.
Model receipt and payroll delays and opening receivables to find the lowest projected month-end cash balance.
Insurance-specific planning
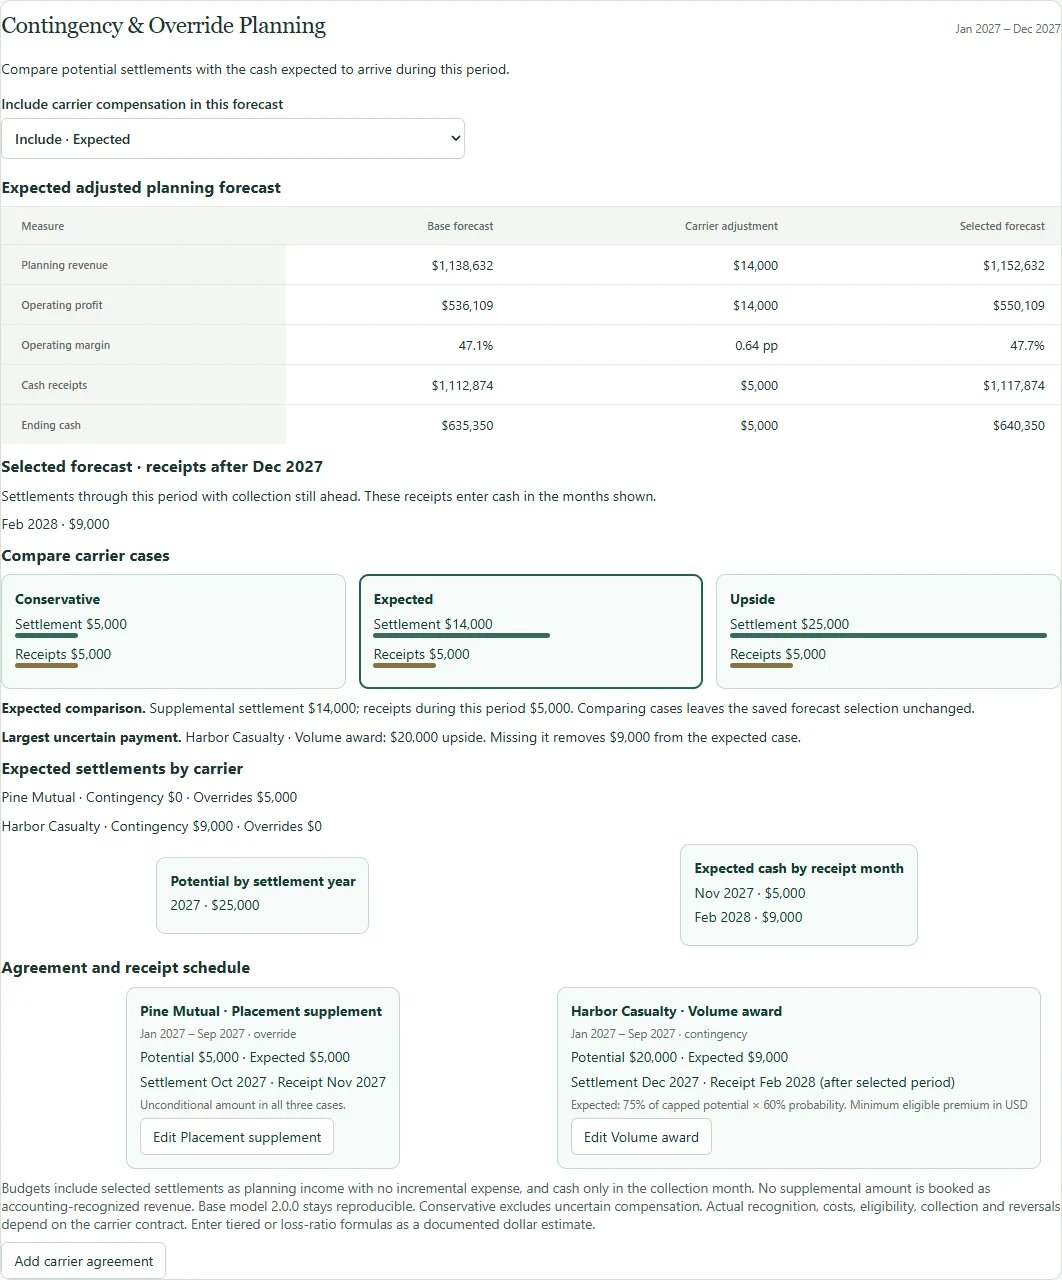
Contingency & Override Planning shows what carrier compensation could add to the year, and when the cash would arrive, without mixing uncertain income into the base forecast.
These are planning estimates. Qualification is not guaranteed, nothing is booked as accounting revenue or receivables, and actual recognition, timing and amounts depend on the carrier contract.
New business & book movement
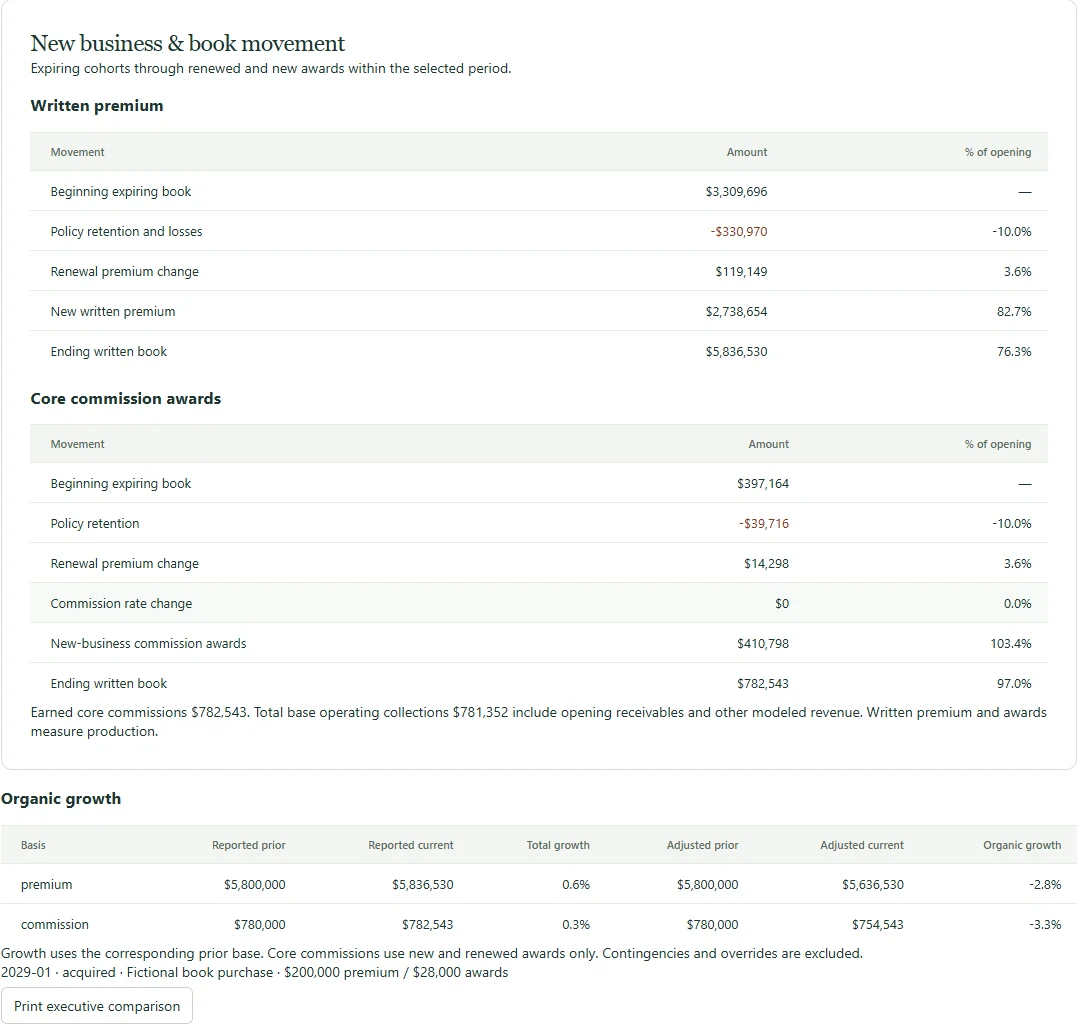
Follow the expiring book through the forecast period: policy retention and losses, renewal premium change and new written premium. The same bridge runs for core commission awards, adding commission-rate change and new-business commission awards.
Renewal Commission Bridge
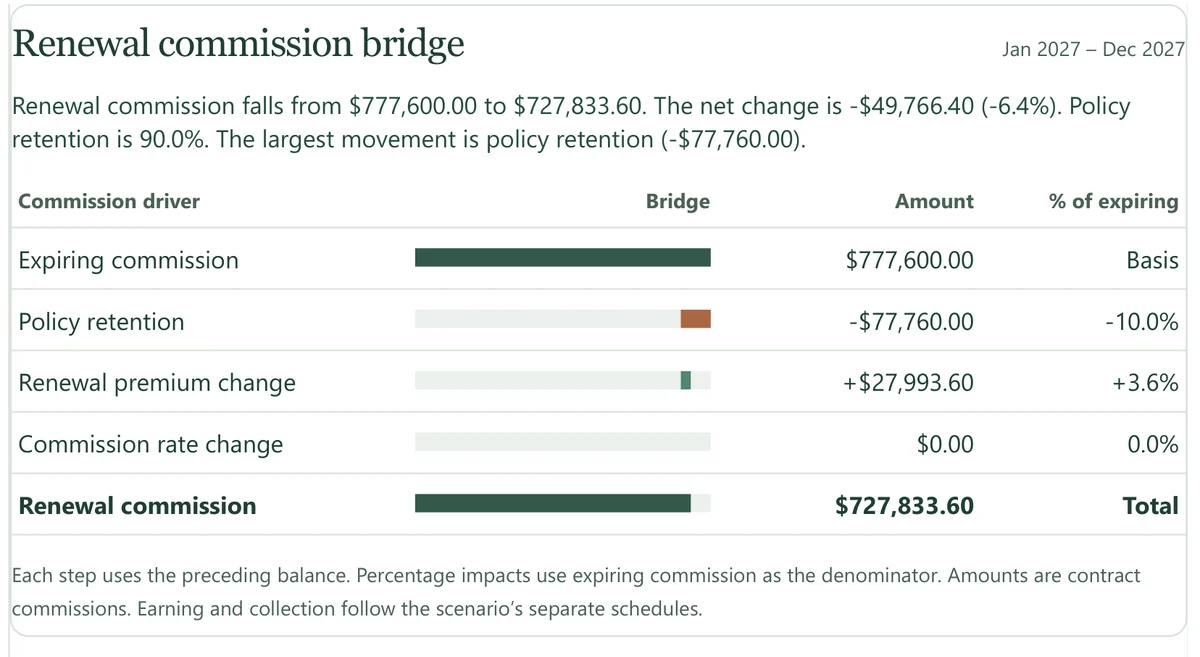
The Renewal Commission Bridge walks from expiring commission to renewal commission, one driver at a time: policy retention, renewal premium change and commission-rate change. It names the largest movement, so you know which conversation to have with carriers, producers or clients.
Actual vs. Budget
Once an Original Budget is finalized, record each month’s actual results and see where the year is heading. Operating performance and cash movement stay separate, so a profitable month and a cash-short month are both visible.
Enter figures directly or import a CSV using the downloadable template. Changes are previewed before saving, and every entry and correction is kept in a revision history.
Monthly and year-to-date budget, actual, dollar variance and percentage variance, with favorable or unfavorable indicators. No percentage is shown when the budget is zero.
Combine actual results for closed months with the forecast for the remaining months to see the projected full year. The finalized Original Budget is never overwritten.
Operating revenue, payroll and compensation, and other operating expenses, with operating profit calculated from them.
Total cash receipts and disbursements, ending cash, ending receivables and ending payroll payable.
The Executive Overview and Executive Financial Report show budget, actual results and the revised outlook, and the comparison can be exported to CSV.
For agencies, Actual vs. Budget also tracks new written premium, new and renewal commission awards, producer payroll and contribution, and contingency and override receipts. Written premium and commission awards measure production; operating revenue is what the agency earned; carrier receipts are cash. Each is recorded and compared separately. Contingency and override planning cases are budget assumptions and never become actual results; actual receipts are entered when received.
Owners and Editors record actual results; Viewers can review them. Actual results come only from figures you enter or import; nothing is filled in automatically.
Multi-year planning
Insurance Agency Lab plans more than one year. Turn a forecast into a finalized budget, revise it as the year develops, and roll balances and recurring assumptions into the next fiscal period, with renewal cohorts and carrier agreement dates reviewed rather than assumed.
Organization owners finalize budgets and carry forward; Editors can save new drafts and Viewers can review saved versions. Results are forecast projections; partial periods are not annualized.
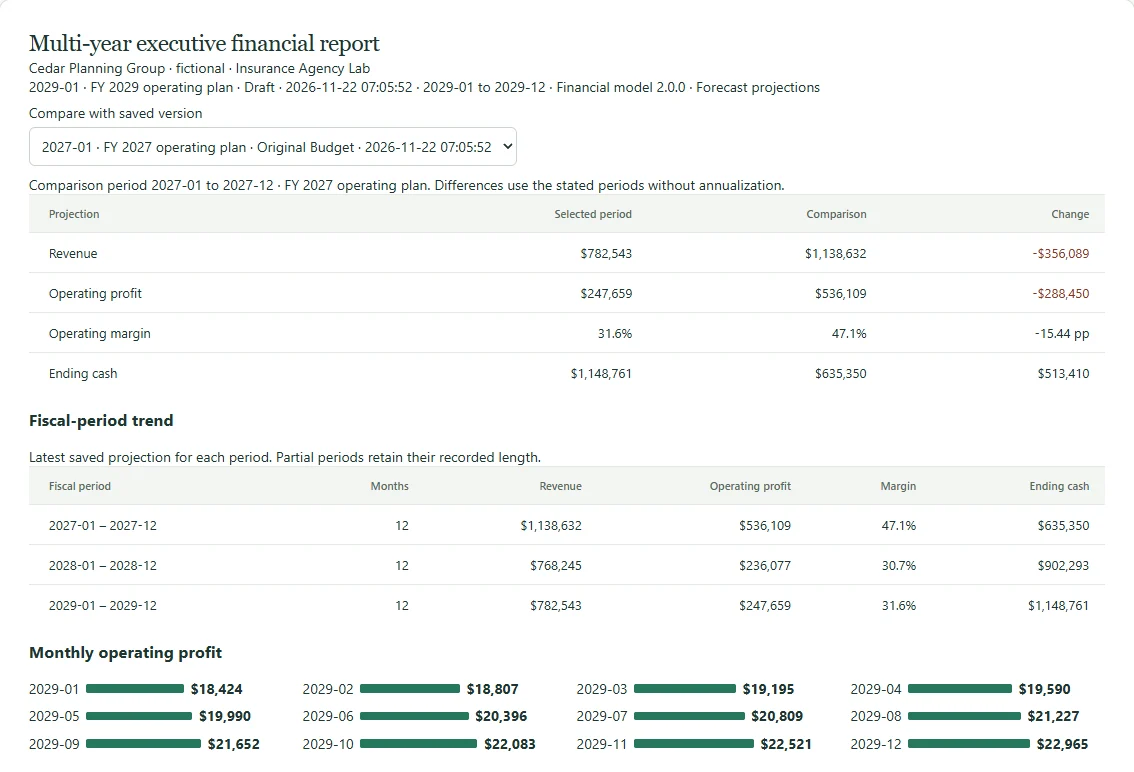
Executive reporting
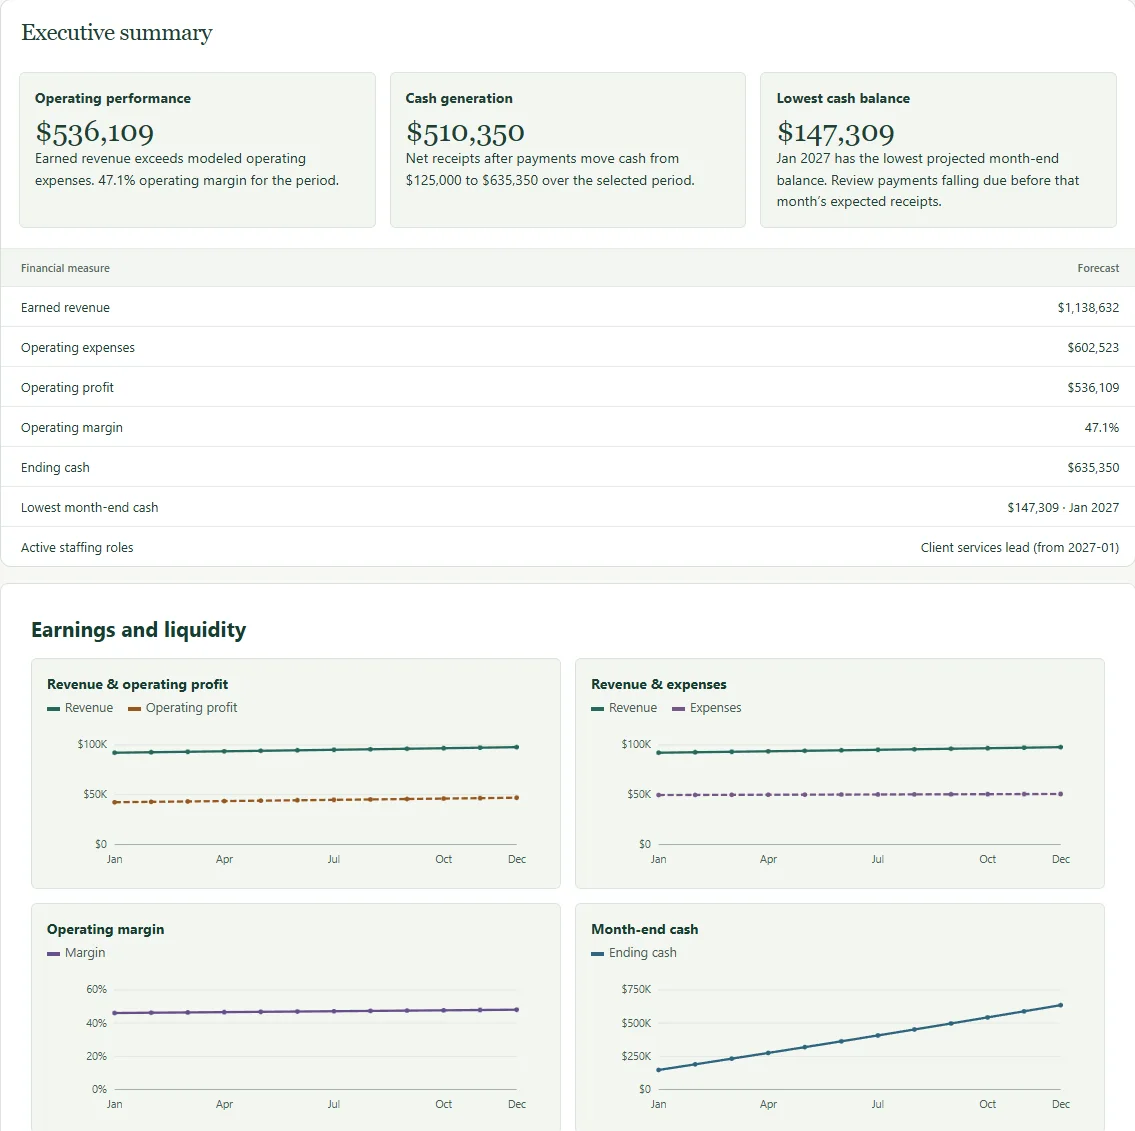
The executive financial report turns the forecast into something you can review with a partner, a lender or your team.
Scenarios and decisions
Keep a base case alongside growth, hiring or downside alternatives and return to them later.
Compare two scenarios side by side and see which drivers explain the difference in profit and cash.
Guided setup and decision guides walk through common agency questions step by step.
Interactive demo
In the fictional book, 90 of 100 policies renew. Cutting commission from 10% to 8% leaves the agency with $7,200 of the $10,000 in expiring commission. Policy retention holds at 90% while commission revenue retention falls to 72%.
The demo also lets you change a new producer’s monthly revenue target and pay split, or move collections into February to see why a profitable January can still finish short of cash.
Try interactive demo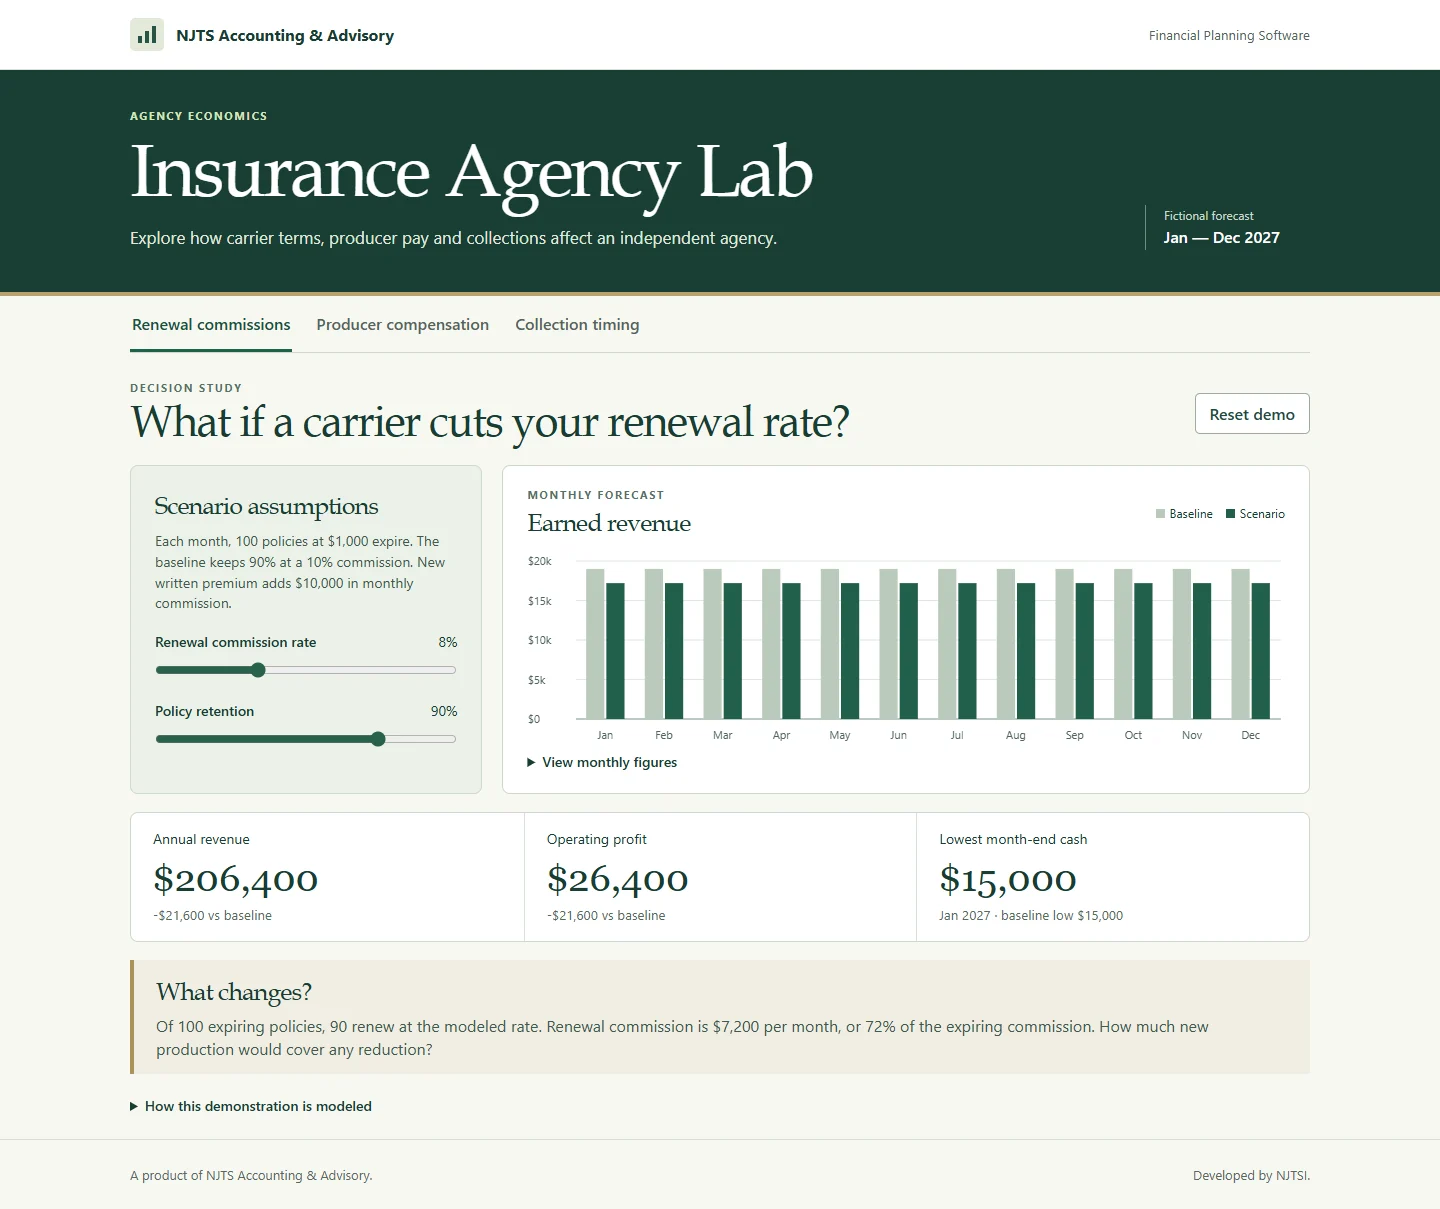
Pricing
Try the full Insurance Agency Lab for 14 days without a credit card. Nothing is charged when the trial ends; a paid monthly subscription is a separate choice.
$39.99per organization
per month
14-day free trial. No credit card required.
No. The 14-day free trial starts with an email address and no payment details.
Nothing is charged automatically, because no card was provided. To keep working in the Lab, choose a paid monthly subscription.
No price increase is currently scheduled. New Insurance Agency Lab subscriptions are $39.99 per organization per month, and the price that applies is confirmed at checkout. Existing subscriptions continue at their agreed price, and any future change is governed by the subscription terms.
No. The demo uses fictional figures and bounded sliders. Reload or select Reset demo to return to the starting assumptions.
The model covers renewal and new-business commission, retention, producer splits and collection timing. Carrier contingencies and overrides can be added as planning estimates with Conservative, Expected and Upside cases. Higher-tier schedules, loss-ratio formulas, clawbacks, midterm cancellations, returns and fiduciary cash flows need contract review; enter a complex arrangement as a documented estimate.
Yes. Subscriptions are priced per organization, not per user. The organization owner can invite Editors and Viewers, such as a partner, manager or outside accountant, and they do not need a subscription of their own. The owner prepares each invitation in the Lab and sends it from their own email app, which opens a ready-to-send message. Invitations expire after seven days, and the owner can withdraw an invitation or remove access at any time.
No. Insurance Agency Lab is for financial planning and decision analysis. It does not replace your agency management system, your books or professional advice. Financing and distributions are outside the forecast, and forecasts are estimates.
Yes. NJTS Accounting & Advisory provides insurance agency accounting and finance advisory, separately from the software.
A product of NJTS Accounting & Advisory. Developed by NJTSI.